
A Looming Deadline for Australian Non-Profits

The deadline for the ATO Self-Review is March 31st and many Australian Non-profits are yet to complete the task.
The ATO introduced the new Not-for-Profit (NFP) Annual Self-Review process in the 2021-22 Federal Budget. It applies to all non-profit organisations with an Australian Business Number (ABN) that are not registered as charities with the Australian Charities and Not-for-Profits Commission (ACNC).
The ATO’s self-review process aims to ensure that only eligible organisations maintain their income tax exemption, enhancing transparency and fairness within the NFP sector. In the return, organisations must provide detailed information about their activities, governance, and specify their tax-exempt category.
Approximately 150,000 Australian non-profit organisations that currently benefit from the income tax exemption could be at risk of losing their status due to new annual reporting requirements introduced by the Australian Taxation Office (ATO). With the March 31st deadline fast approaching, many community groups remain unaware of the significant implications of the self-review process.
With the deadline just around the corner, organisations must act now to remain compliant and maintain their tax exempt status, if indeed they are eligible.
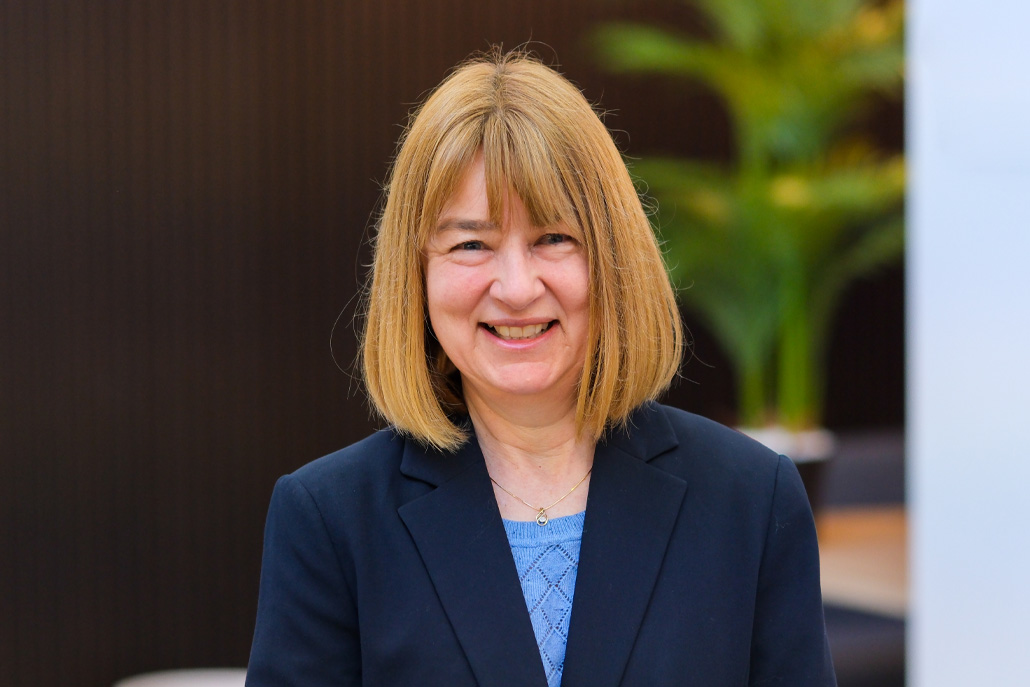
“Many organisations have assumed they can simply self-assess their income tax exemption,” warns Cathy Braun, a tax advisor at accounting firm Saward Dawson “They cannot. Even if they fall within one of the self-assessment categories, they cannot use it if they are a charity. A charity must be registered with the ACNC to be income tax exempt.”
Braun’s urgent advice is clear: “Seek expert advice on completing the Self-Review. Many groups will ultimately find that they are not eligible and should either be a registered charity or are taxable.”
The financial impact of losing the income tax exemption can vary significantly among organisations. Some may find they have tax losses, resulting in no tax payable, while others could face substantial tax liabilities. Additionally, non-compliance may damage an organisation’s reputation, highlighting the importance of proactive compliance.
With the right advice, it may be that organisations still qualify for a tax exemption even if their initial assessment suggests that they are not exempt.